Consolidate High-Interest Debt
Use available home equity to pay off higher-interest credit cards or other eligible debts and potentially simplify your monthly payments.
Access the equity you've built without automatically giving up your existing mortgage rate. Explore your HELOC options online, with an initial soft credit inquiry and funding in as few as 5 days for eligible borrowers.
Check your initial options with no impact to your credit score.
Soft Credit Check to Start
Explore initial HELOC options without a hard credit inquiry.
Fast, Online Process
Get started in minutes and review available options.
Funding in as Few as 5 Days
Eligible borrowers may receive funding in as few as five days, subject to approval and closing requirements.
Initial prequalification uses a soft credit inquiry. Continuing with a full application may require a hard credit inquiry. Funding times vary. All loans subject to credit approval and program eligibility.
Benefits
Your home may be one of your biggest financial assets. A Home Equity Line of Credit can help you put some of that value to work while keeping your existing mortgage in place.
Use available home equity to pay off higher-interest credit cards or other eligible debts and potentially simplify your monthly payments.
Renovate your kitchen, update your bathroom, replace your roof, or make the improvements you've been planning.
Life happens. Home equity may help cover significant unexpected expenses when you need financial flexibility.
Access funds for planned large expenses without automatically refinancing your existing first mortgage.
Eligible property owners may use home equity to pursue financial opportunities, subject to lender guidelines.
Help fund major family expenses, education costs, or other important financial priorities.
Whatever your goals, understanding your available home equity is the first step.
See How Much Equity You Could Access(opens in a new tab)Using home equity to consolidate unsecured debt converts that debt into debt secured by your home, and failure to repay could result in foreclosure. Tax treatment varies.
Why choose this HELOC
With a second-lien HELOC, you may be able to access equity without refinancing your current first mortgage.
Depending on eligibility, loan terms may be available for 10, 15, 20, or 30 years.
HELOC options may be available for eligible primary residences, second homes, and investment properties, depending on state and program requirements.
Begin online from home and complete many steps digitally.
Certain closing and origination fees may be financed into the loan instead of paid separately upfront. Fees still apply and increase the amount financed.
During the applicable draw period, principal payments may restore available credit for additional draws, subject to the loan agreement.
HELOC features and qualification requirements vary. This program includes a required initial draw of the full credit amount at closing. Additional borrowing is subject to the applicable draw-period terms.
How it works
Start with a quick online inquiry to explore your potential HELOC options. The initial inquiry uses a soft credit check.
If eligible, review your available options and continue the application. Income, credit, property, identity, and other information may require verification.
Once approved and closing requirements are satisfied, funds can be delivered electronically. Eligible borrowers may receive funding in as few as five days.
No initial hard credit inquiry. No obligation to accept an offer.
Refinancing your entire mortgage isn't always necessary when you need cash. A second-lien HELOC can let qualified homeowners access available equity while leaving their existing first mortgage in place.
Neither option is right for everyone. Compare rates, fees and terms. Read the full comparison.
A quick initial eligibility check can help you explore potential HELOC options without affecting your credit score.
Get started online without visiting a branch.
Funding may be available in as few as five days, depending on the property, approval, closing, and applicable waiting periods.
An initial eligibility result is not a final loan approval. Final approval requires a full application, which may include a hard credit inquiry and verification of income, identity and property.
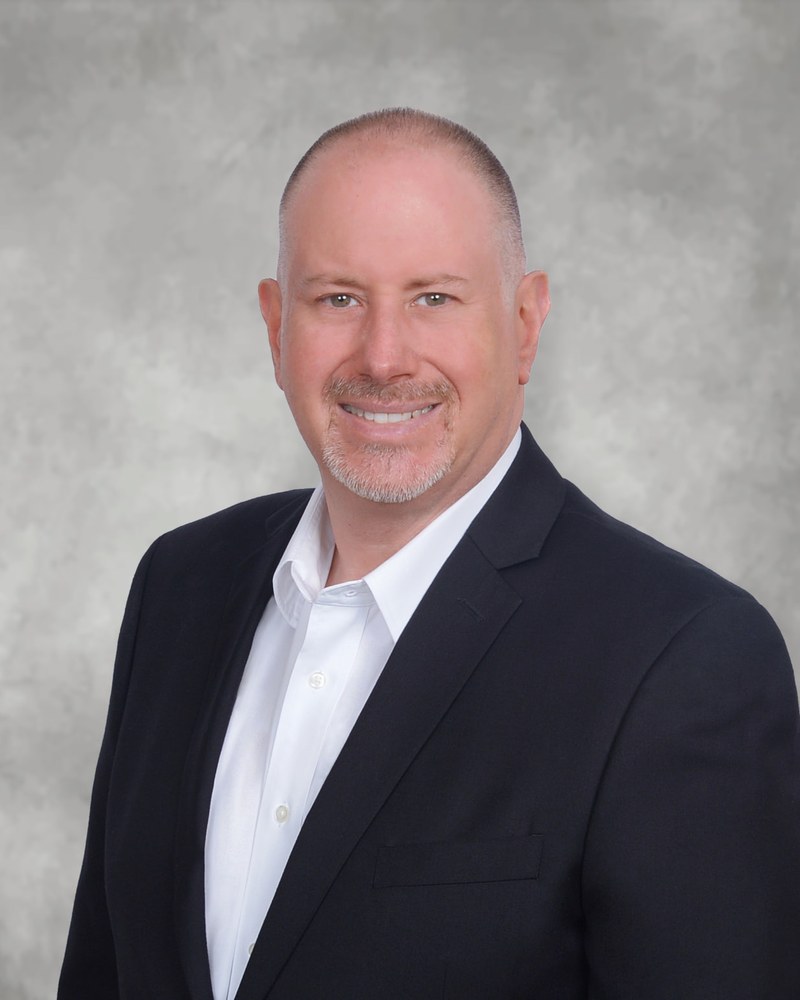
Sean Segaloff · Mortgage Broker | NMLS #353031
MWS Mortgage Solutions | NEXA Lending · Branch NMLS #2346387 · Company NMLS #1660690
At MWS Mortgage Solutions, I believe mortgages shouldn't be complicated — they just need to be explained clearly.
My goal is to help homeowners understand their options, make informed decisions, and find financing that fits their needs.
Whether you're exploring a HELOC to consolidate debt, improve your home, or cover a major expense, I'm here to help you understand the process.
FAQs
A Home Equity Line of Credit (HELOC) is financing secured by your home that allows eligible homeowners to access a portion of their available equity.
A HELOC is different from a traditional personal loan because your home serves as collateral. HELOC structures vary by lender, including how initial funds are disbursed and when additional draws are permitted.
The initial prequalification inquiry uses a soft credit check, which does not affect your credit score.
If you decide to move forward with the full application, a hard credit inquiry may be required.
Eligible borrowers may receive funding in as few as five days, but timing is not guaranteed.
The actual timeline depends on credit approval, income verification, property valuation, closing, any applicable rescission period, and bank processing.
After funds are disbursed, ACH processing may take an additional two to three business days, depending on the financial institution.
Yes, potentially. A second-lien HELOC allows qualified borrowers to access home equity without replacing their existing first mortgage.
You will have a separate HELOC obligation in addition to your existing mortgage.
The featured HELOC program offers potential credit amounts generally ranging from $25,000 to $750,000. The minimum is $35,000 in Texas.
Actual eligibility and available loan amounts depend on the property's location, value, existing liens, credit profile, income, and applicable program requirements. Not all borrowers qualify for the maximum amount.
Available options depend on your complete credit and financial profile.
Certain primary-residence program options may consider credit scores beginning at 600, but not everyone at that score will qualify.
Minimum scores may be higher for second homes, investment properties, larger loan amounts, and other circumstances.
Yes. HELOC proceeds may be used for eligible debt consolidation.
However, consolidating unsecured debt through a HELOC makes that debt secured by your property. Your home could be at risk if you do not repay the loan.
Not always.
An automated property valuation may be available for certain applications.
A full appraisal is required for loan amounts above $400,000 under the featured program. Other applications may require additional property valuation.
For the HELOC program featured on this website, 100% of the initial approved credit amount is drawn at closing.
This differs from traditional HELOCs that may allow smaller initial withdrawals. Repayment obligations are based on the funded loan balance and applicable loan terms.
As principal is repaid, eligible borrowers may be able to access available credit again during the applicable draw period, subject to program requirements.
Yes.
A HELOC is secured by your home. Failure to make required payments or satisfy the loan agreement could result in foreclosure.
Make sure the loan and its payments fit your financial situation.
Yes, eligible self-employed borrowers may qualify for a HELOC.
The featured program offers several supported methods of income verification, potentially including connected personal or business bank accounts, financial assets, and tax information.
The lender determines qualifying income based on the available documentation and program guidelines. Business bank deposits do not automatically equal qualifying income.
Certain HELOC programs allow financing on eligible investment properties and second homes.
Availability depends on your state, property, credit profile, and other lender requirements.
Yes, eligible condominiums may qualify.
Lender guidelines, property value, location, credit profile, and other factors determine eligibility.
Fees can apply, including origination and valuation-related fees.
Under certain available programs, eligible fees may be included in the loan balance rather than paid separately upfront.
Financing fees does not eliminate them.
Potentially, yes.
As you repay your line balance, available credit may be restored during the applicable draw period.
Additional draws are subject to program rules, minimum draw requirements, and the credit limit. Additional draws may carry different interest rates and affect monthly payments.
HELOC rate structures vary.
The featured program may offer a fixed or variable rate for the initial funded amount, depending on eligibility and availability.
Additional draws may have their own rates.
Review the actual offer and loan agreement before proceeding.
The featured program allows early repayment without a borrower prepayment penalty.
Always review the final loan terms and disclosures for applicable fees, conditions, and requirements.
Potentially.
For this program, waiting approximately 45 days after your refinance has been recorded may help ensure the existing mortgage information is accurately reflected.
Not necessarily.
Depending on property ownership and state requirements, a spouse or another titleholder may need to sign certain mortgage documents without becoming a borrower.
Specific requirements vary by state and transaction.
Eligible property types may include single-family homes, townhomes, eligible condominiums, duplexes, and certain two-to-four-unit properties.
Occupancy, state restrictions, and property-specific underwriting requirements apply.
The online application uses security measures intended to protect borrower information.
For security and privacy details, applicants should review the privacy notices and security information provided in the application.
If you receive available options, you can review them and decide whether to continue.
Moving forward may involve a hard credit inquiry, identity verification, income verification, a property review, and closing documentation.
You are not required to accept an offered loan simply because you checked your initial options.
Whether you're planning renovations, consolidating debt, or preparing for a major expense, exploring your HELOC options is a simple first step.
See How Much Equity You Could Access(opens in a new tab)Initial soft credit inquiry. No obligation to accept an offer.